Cheap Car Insurance: How to Lower Your Premium Without Losing Coverage
Kicking off with Cheap Car Insurance: How to Lower Your Premium Without Losing Coverage, this opening paragraph is designed to captivate and engage the readers, providing a glimpse into the world of cost-effective car insurance without compromising coverage. Exploring the various strategies and factors that play a role in determining insurance premiums, this article aims to equip readers with valuable insights to make informed decisions about their car insurance needs.
When it comes to determining car insurance premiums, several factors come into play that can significantly impact the amount you pay. Let’s explore some of the key factors influencing your car insurance rates.
Age plays a crucial role in determining car insurance premiums. Generally, younger drivers under the age of 25 tend to pay higher premiums due to their lack of driving experience and higher likelihood of being involved in accidents.
Your location can also affect your car insurance rates. Urban areas with higher population densities and increased traffic congestion typically have higher premiums compared to rural areas with lower traffic volume and fewer accidents.
Your driving record is a major factor that insurance companies consider when determining your premiums. A clean driving record with no accidents or traffic violations will generally result in lower insurance rates, while a history of accidents or traffic tickets can lead to higher premiums.
The type of car you drive can impact your insurance rates as well. Factors such as the make and model of your vehicle, its age, safety features, and likelihood of theft all play a role in determining your premiums. Generally, newer, more expensive cars will have higher insurance costs.
The coverage limits you choose for your car insurance policy also affect your premiums. Opting for higher coverage limits will result in higher premiums, but it can provide more protection in the event of an accident. On the other hand, choosing lower coverage limits can lower your premiums but may leave you financially vulnerable in case of a serious accident.
Believe it or not, your credit score can also influence your car insurance rates. Insurance companies often use credit information to predict the likelihood of a policyholder filing a claim. Those with higher credit scores typically receive lower insurance premiums, while those with lower credit scores may face higher rates.
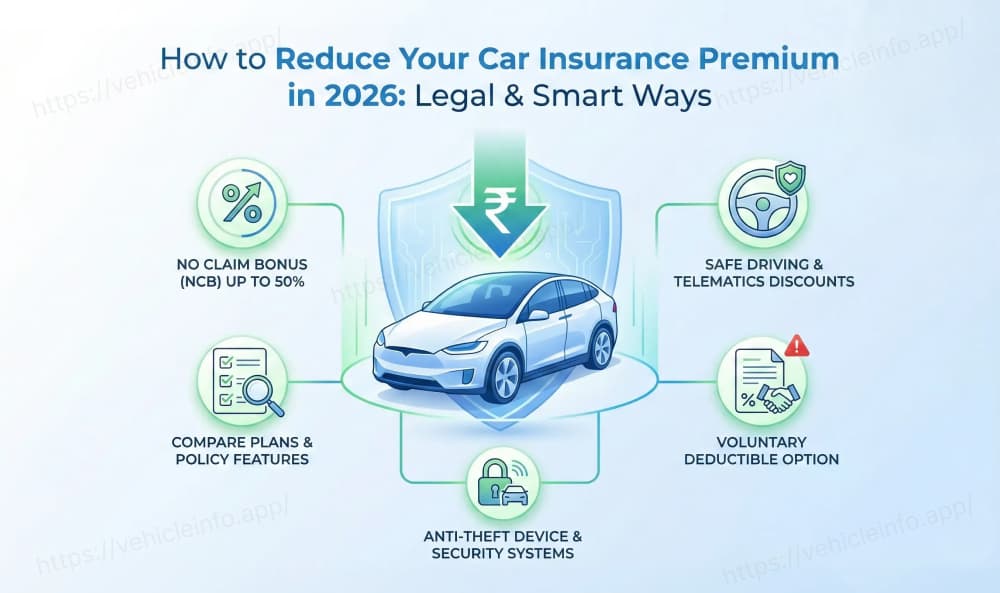
When it comes to reducing your car insurance premiums, there are several strategies you can consider. From bundling policies to increasing deductibles, these tactics can help you save money without sacrificing coverage.
By combining your auto insurance policy with other insurance products, such as homeowners or renters insurance, you can often qualify for a multi-policy discount. This bundling can result in significant savings on your overall insurance costs.
One way to lower your premiums is by opting for a higher deductible. A deductible is the amount you pay out of pocket before your insurance coverage kicks in. By increasing your deductible, you can reduce your premiums, but keep in mind that you’ll have to pay more in the event of a claim.
Having a clean driving record free of accidents and traffic violations can also help lower your car insurance premiums. Insurance companies typically offer lower rates to drivers with a history of safe driving, so it’s important to drive responsibly and avoid speeding tickets and accidents.
When it comes to lowering your car insurance premium, taking advantage of discounts and savings opportunities can make a significant impact on your overall costs. Insurance companies offer various discounts to help you save money on your policy. By understanding these discounts and how to maximize them, you can potentially reduce your premium while still maintaining adequate coverage.
When it comes to finding affordable car insurance, comparison shopping is essential. By getting quotes from different insurance providers, you can ensure that you are getting the best coverage at the most competitive price.
It’s important to compare quotes from multiple insurance companies to make sure you are not overpaying for coverage. Each insurance provider has its own way of evaluating risk and setting premiums, so prices can vary significantly between companies.
When comparing coverage options and premiums, it’s important to look beyond just the price. Consider the level of coverage offered, the deductible amount, and any additional benefits included in the policy.
Remember, the cheapest policy may not always provide the best coverage, so make sure you are comparing apples to apples.
Independent insurance agents or online comparison tools can be valuable resources in helping you find affordable coverage. These professionals can help you navigate the insurance market and find the best policy to meet your needs and budget.
Independent agents can provide personalized service and help you understand your coverage options, while online tools can quickly generate quotes from multiple insurance companies for easy comparison.
Usage-based insurance, also known as telematics insurance, is a type of auto insurance that uses data collected from a device installed in your vehicle to determine your premium. This device, called a telematics device, tracks your driving behavior, such as speed, braking, and mileage, to assess your risk level accurately.
Telematics devices have a significant impact on insurance premiums as they provide insurers with real-time data on how you drive. By analyzing this data, insurers can offer personalized premiums based on your actual driving habits rather than general risk factors, potentially leading to lower premiums for safe drivers.
Your driving behavior plays a crucial role in determining your insurance rates under a usage-based insurance model. Safer driving habits can result in lower premiums, while risky behavior may lead to higher costs. It incentivizes drivers to adopt safe practices and ultimately save money on their insurance.
How can my credit score impact my insurance rates?
Your credit score can influence your insurance rates as insurance companies often use it as a factor to determine your level of risk. A higher credit score typically leads to lower premiums.
What are some common discounts available for car insurance?
Common discounts include multi-policy discounts, safe driver discounts, good student discounts, and discounts for safety features in your car.
How does usage-based insurance work?
Usage-based insurance uses telematics devices to track your driving behavior, such as mileage, speed, and braking. By demonstrating safe driving habits, you can potentially lower your insurance premiums.